
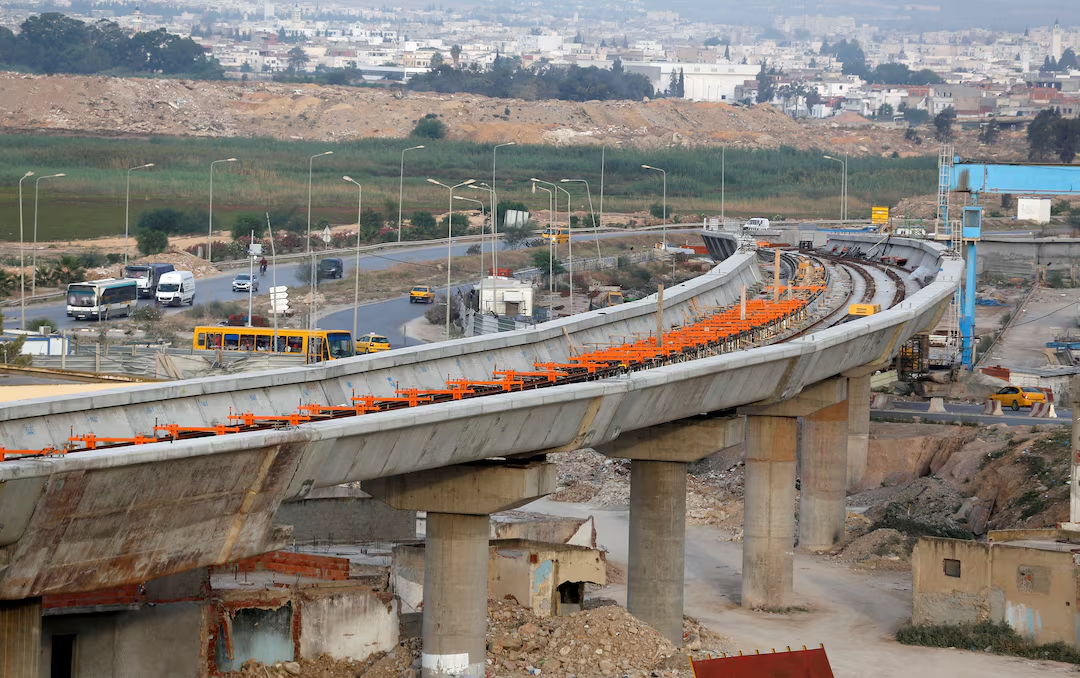
African governments facing expensive borrowing, limited access to capital and growing debt pressures are increasingly looking for ways to finance infrastructure without placing additional strain on public finances.
One option attracting greater attention is asset recycling — a model that allows governments to raise capital from existing public infrastructure while retaining ownership of the underlying assets.
The approach could provide governments with a new source of funding for roads, transport networks, utilities and other infrastructure projects at a time when traditional sources of public financing are becoming increasingly constrained.
How asset recycling works
Under an asset-recycling arrangement, a government gives a private-sector operator the right to operate and earn revenue from an existing public asset for a specified period.
In exchange, the government receives an upfront payment.
The private operator then takes responsibility for improving the asset’s operations, efficiency and commercial performance during the concession period.
The government retains ownership of the underlying infrastructure, while the money generated from the transaction can potentially be redirected towards the development of new infrastructure.
That creates the possibility of turning existing public assets into a source of capital for future projects without governments having to sell those assets permanently.
The proceeds could also attract additional financing from development finance institutions, pension funds, private-equity investors and other sources of private capital.
Why governments are paying attention
The model is particularly relevant at a time when many African governments face competing demands on limited budgets.
Public funds must cover areas such as healthcare, education and social programmes, while infrastructure projects require substantial long-term investment.
Traditional borrowing can provide some of the necessary capital, but higher financing costs and rising debt burdens can make additional government borrowing difficult.
Asset recycling offers another route.
Instead of waiting for a government budget or new debt to finance an infrastructure project, authorities can potentially use the value tied up in an existing asset to generate capital for new development.
The private sector, meanwhile, takes on much of the operational responsibility and investment required to improve the asset.
Not the same as privatisation
One of the biggest sources of confusion around the model is its similarity to privatisation.
Both approaches can involve private companies taking over the operation of state-owned infrastructure.
The key difference is ownership.
Under asset recycling, the state continues to own the underlying asset while granting a private operator rights to operate it for a defined period.
That distinction can be important when the infrastructure involved provides essential public services.
However, the arrangement can still generate public concern, particularly when citizens fear that private operators could increase prices, reduce access or place commercial interests ahead of public needs.
Governments therefore need to communicate clearly about how each transaction will work and what protections will remain in place for consumers.
Not every asset is suitable
Asset recycling also comes with significant limitations.
A public asset cannot automatically become an attractive investment simply because a government owns it.
Potential investors need to see a viable commercial model, predictable regulations and sufficient revenue potential.
Some state-owned enterprises may require major restructuring before they can attract private capital. Tariff policies, environmental requirements, regulatory restrictions and existing contractual arrangements can also make transactions more complicated.
Governments must therefore assess assets carefully before putting them forward for recycling.
Transparency is equally important.
If authorities overestimate an asset’s value or conduct negotiations without sufficient openness, the resulting transaction could fail to deliver the expected benefits.
Choosing a private partner based solely on the largest upfront payment can create another problem.
The highest bidder may not necessarily have the technical expertise, financial strength or long-term strategy required to operate the asset effectively.
A poorly chosen concessionaire could ultimately damage the infrastructure and undermine public confidence in the entire model.
Where should the money go?
Perhaps the most important question is what governments do with the proceeds.
The purpose of asset recycling is to unlock capital for new productive infrastructure.
If the money is simply used to cover recurring government expenses or close short-term budget gaps, the long-term benefits of the transaction could be significantly reduced.
Strong rules around how proceeds are allocated can therefore be critical.
Governments could, for example, establish clear frameworks requiring funds to be directed towards infrastructure projects capable of generating broader economic value.
Without such safeguards, asset recycling could become little more than a temporary fiscal measure.
Building confidence around the model
A broader institutional framework may also be needed before asset recycling can become a mainstream infrastructure-financing tool across Africa.
Governments, investors, development finance institutions, pension funds and other stakeholders need clear rules covering how assets are selected, valued, tendered and transferred to private operators.
Legal certainty and transparent procurement processes can help reduce investor risk while protecting the public interest.
Africa50 has been identified as a potential catalyst for developing approaches and frameworks that individual countries could adapt to their own markets.
Such coordination could help governments learn from previous transactions and avoid repeating costly mistakes.
Asset recycling is therefore not a solution to every infrastructure-financing challenge facing Africa.
But if governments select appropriate assets, structure concessions carefully, protect consumers and ensure that proceeds are reinvested productively, the model could become another tool for mobilising capital.
For countries struggling to balance infrastructure needs against limited fiscal space, the ability to unlock value from assets they already own could prove increasingly important.
